
When Your Income Isn't Keeping Up With Your Debt, There May Be a Better Way Forward.
Debt Guidance helps over-indebted South Africans restructure unaffordable debt repayments through the regulated debt-review process. Combine multiple repayments into one manageable monthly payment and work toward becoming debt-free under the National Credit Act.
Get My Free Debt Assessment
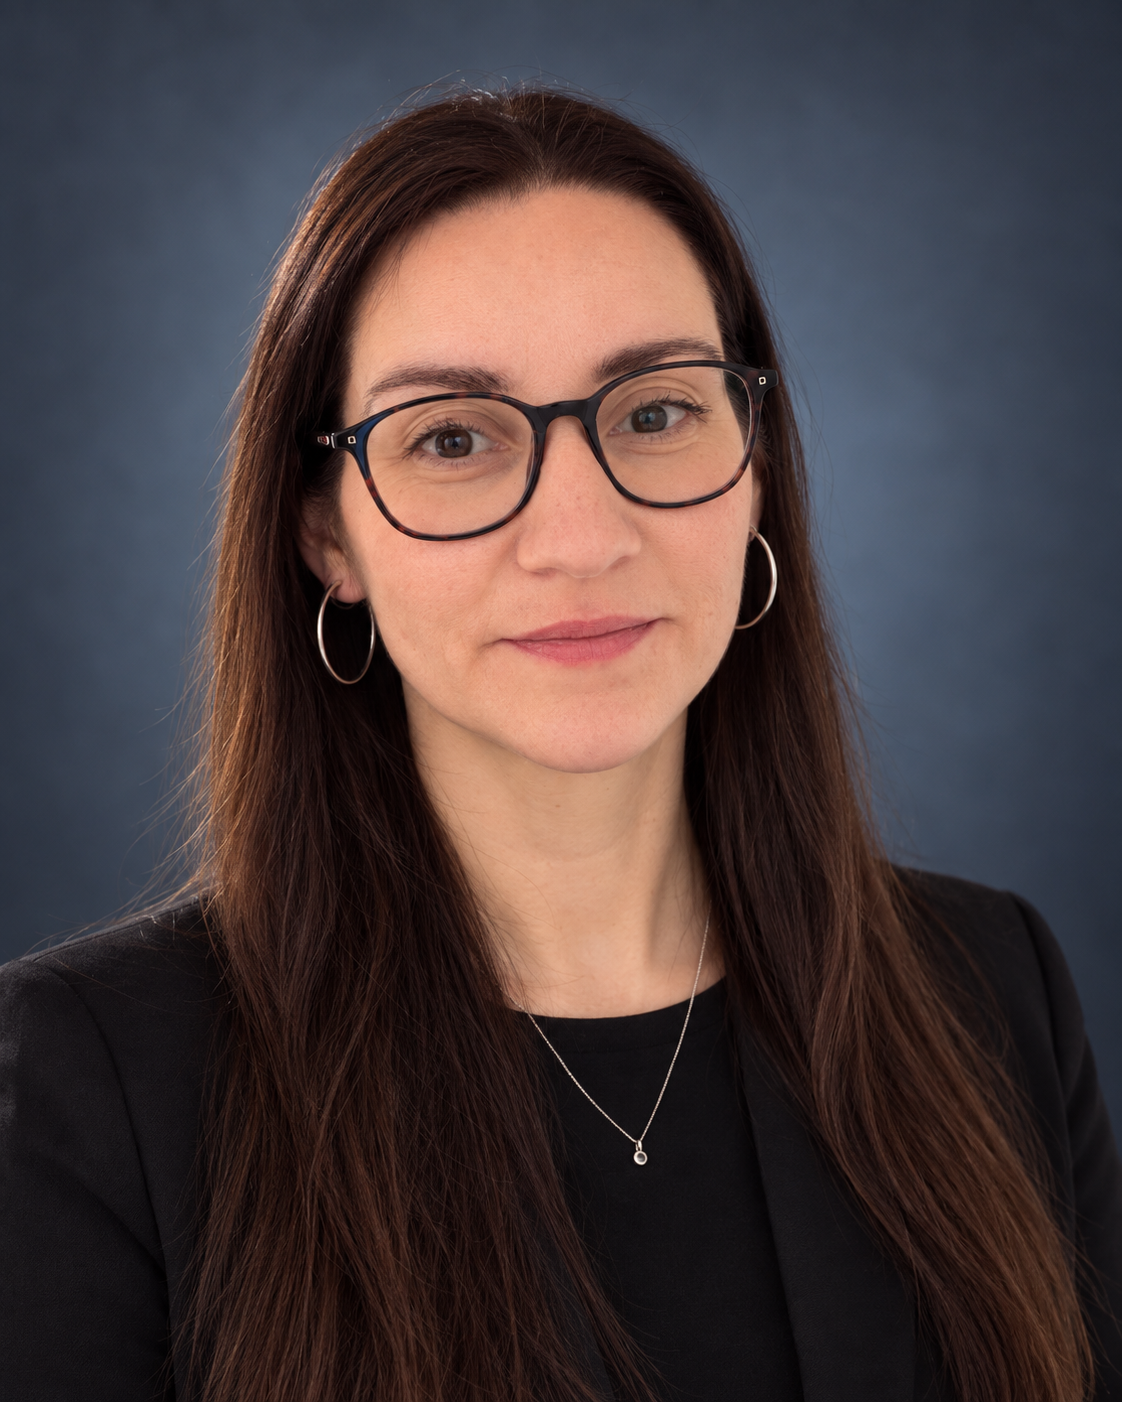
Confidential review with registered debt counsellor Carolina Guevara Harris (NCRDC3152)
National Credit Regulator verified
Dedicated debt counselling experience
Clients who completed the full process
Serving South Africans anywhere online & phone
Do These Debt Problems Sound Familiar?
When debt spirals, it is rarely due to poor character. Rising living costs, fuel prices, interest rate hikes, and family emergencies place extreme strain on honest South African households.
Most of your salary goes to debt
After monthly instalments are debited on payday, there is barely enough left over for groceries, school fees, and electricity.
Using one credit card to pay another
You find yourself drawing cash advances, using revolving credit, or taking retail account limits to cover essential payments.
Loans and credit cards unaffordable
Compound interest and banking fees mean balances stay stubbornly high despite months of dutiful monthly payments.
Falling behind on car or home loans
Missed asset finance instalments create immediate anxiety regarding potential vehicle repossession or foreclosure summons.
Constant calls from collection agents
Relentless phone calls, SMS reminders, and legal threats disrupt your workday and create unbearable personal and family stress.
Living in perpetual financial survival
There is zero margin for family emergencies, savings are depleted, and the prospect of becoming debt-free feels impossible.
Being over-indebted is not simply a budgeting problem. South African law provides a regulated process designed to assist qualifying consumers.
What Is Debt Review in South Africa?
Introduced under Section 86 of the National Credit Act No. 34 of 2005, debt review is not a new loan, bankruptcy, or blacklisting. It is a statutory rehabilitation framework where an NCR-registered debt counsellor acts as an intermediary between you and your credit providers.
By presenting an objective, court-sanctioned budget, your debt counsellor can renegotiate unaffordable instalments and reduced interest rates. A single consolidated monthly payment is then distributed to all your creditors via an NCR-accredited Payment Distribution Agency (PDA).
How the Debt Review Process Works
A transparent, regulated journey from your initial confidential assessment to full credit clearance.
Free Financial Assessment
We review your net household income, essential living expenses, and all monthly debt obligations.
Determine Over-Indebtedness
A registered debt counsellor formally assesses whether you meet the statutory requirements of Section 79.
Restructuring Proposal
Where appropriate, revised repayment terms and concessionary interest rates are proposed to creditors.
Formal Legal Process
The restructuring proceeds through the applicable creditor negotiations and court or NCT consent order.
Complete Programme
Once qualifying debts are settled, your debt counsellor issues your official Form 19 clearance certificate.
How Debt Review May Help
Debt counselling provides an orderly, regulated framework to regain control of your household finances.
One structured monthly repayment
Instead of managing multiple debit orders across different banks, you pay a single consolidated amount to a registered Payment Distribution Agency (PDA).
More manageable repayments
Repayment terms may be extended and interest rates negotiated down where creditors agree, significantly lowering monthly cash flow obligations.
Professional creditor negotiation
Debt Guidance deals directly with all registered credit providers, handling queries, negotiations, and restructuring submissions on your behalf.
Protection through regulated process
While under formal debt review and maintaining payments, credit providers cannot independently proceed with new legal enforcement or repossession.
Defined path to becoming debt-free
You receive a clear repayment plan with projected settlement dates, ending the cycle of endless interest and fees without debt reduction.
Clearance certificate once settled
Once qualifying debt is repaid, your debt counsellor issues a Form 19 clearance certificate, requiring credit bureaux to clear all debt review records.
Why South Africans Entrust Their Financial Recovery to Debt Guidance
Entering debt review is an important financial decision involving significant obligations. Debt Guidance has been operating as an independent, regulated practice since 2015, helping over 1,000 consumers achieve clearance certificates.
Registered Debt Counsellor: Carolina Guevara Harris
Formally registered with the National Credit Regulator under certificate number NCRDC3152.
Established Practice Since 2015
Over a decade of direct institutional experience negotiating with major South African banks and credit providers.
1,000+ Verified Clearances Achieved
Real consumers who successfully completed their restructuring and had their credit bureau records restored.
Carolina Guevara Harris
NCR Registration: NCRDC3152
Role: Principal Debt Counsellor & Practice Director
Location: Serving all South African provinces
What Debt Guidance Clients Say
Transparent client experiences from South African consumers who navigated debt counselling with us.
“When my car was at risk and my salary was eaten up by interest, Carolina and the team stepped in. They managed to negotiate our instalments down and stopped the collection calls. After 4 years, I now have my Form 19 clearance certificate.”
“Debt Guidance was completely honest with me from day one about what debt review can and cannot do. They didn't make fake promises. They showed me the actual restructuring numbers and helped me save my family home.”
“I was skeptical because there are so many scam debt review companies out there. Knowing Carolina is an actual NCR registered debt counsellor (NCRDC3152) gave me confidence. Professional and supportive team throughout.”
Frequently Asked Questions
Clear, factual answers regarding the debt review process under South African law.
Who qualifies for debt review?
To qualify, you must have a regular source of income (employment, self-employment, or fixed pension) and be legally determined to be “over-indebted” under Section 79 of the National Credit Act.
Read full qualification criteria →Can I keep my car under debt review?
In many cases, yes. Your vehicle instalment can be restructured alongside your other debts, provided formal legal action (such as a summons or cancellation order) has not already commenced prior to applying.
Learn more about vehicle protection →Can interest rates be reduced under debt review?
In many cases, credit providers agree to reduce interest rates on unsecured accounts (credit cards, personal loans, retail accounts) through the industry's concession guidelines (DCRS) to facilitate capital repayment.
How interest rates work under review →Take the First Step Toward Financial Relief Today
Speak directly with registered debt counselling professionals. We will review your income, living expenses, and credit agreements to determine if debt review is the right statutory solution for you.